What Travel Insurance Is Actually Designed to Do
Travel insurance operates on a simple but often misunderstood principle: it covers named perils. That means the policy lists specific situations it will pay out for, and anything not on that list - no matter how disruptive - is not covered. This is fundamentally different from a guarantee against all travel disruption.
The core categories covered by most comprehensive travel insurance policies include:
- Trip cancellation and interruption: Reimburses prepaid, non-refundable costs if you have to cancel or cut short your trip due to a covered reason (typically illness, injury, death of a family member, or certain natural disasters).
- Emergency medical expenses: Pays for hospital care, doctor visits, or treatment if you get sick or injured while traveling, particularly important for international travel where your domestic health insurance may not apply.
- Medical evacuation: Covers the cost of transporting you to an adequate medical facility, which can be extraordinarily expensive without coverage.
- Baggage loss or delay: Reimburses you for lost, stolen, or significantly delayed luggage, usually up to stated limits.
- Travel delay: Provides a daily allowance for meals and accommodation if your trip is delayed beyond a threshold (often 6-12 hours) due to a covered cause.
For a broader look at how these protections play out in practice, see our travel insurance overview.
$50,000+
Typical cost of international air ambulance evacuation
Medical evacuation from remote international locations routinely costs tens of thousands of dollars, according to the U.S. Travel Insurance Association.
~$1,900
Average travel insurance claim amount
The U.S. Travel Insurance Association has reported average claim payouts in this range, with medical and trip cancellation being the most common claim types.
14-21 days
Typical window to add pre-existing condition waiver
Most insurers require purchase of a pre-existing condition waiver within a short window after the initial trip deposit to qualify for that coverage.
Common Exclusions You Need to Know Before You Buy
Understanding what travel insurance doesn't cover is just as important as knowing what it does. Travelers who assume broader coverage than their policy provides are the ones who end up with denied claims.
Pre-existing medical conditions
Most standard policies exclude medical claims related to conditions you had before purchasing the policy. A waiver is often available - but typically only if purchased within a short window after your initial trip deposit, and it comes with its own eligibility requirements.
Foreseeable events and known disruptions
If a hurricane, strike, or outbreak is already in the news when you buy your policy, insurers generally treat it as a foreseeable event and exclude related claims. Insurance is designed to cover the unexpected - not events you were aware of when you purchased coverage.
Pandemic and government travel restrictions
Blanket pandemic coverage is not standard. Some policies have evolved to include COVID-19 as a covered illness for medical claims, but government-mandated border closures or advisories are frequently excluded.
Risky activities and adventure sports
Activities like skydiving, scuba diving, mountaineering, or even skiing may require a specific rider or add-on for coverage. Participating in an excluded activity and getting injured can void your claim entirely.
Financial default of a travel provider
If an airline or tour operator goes bankrupt, standard policies may not cover you unless you've purchased "supplier default" coverage - a separate optional benefit not included in all policies.
A traveler breaks her ankle hiking in Costa Rica and needs emergency surgery at a private hospital, followed by a medical flight back to the U.S.
A traveler books a cruise six months out, then tests positive for COVID-19 two days before departure.
A traveler's checked bag is lost by the airline on a two-week international trip, including a laptop worth $1,800.
A couple cancels a $8,000 European trip because they simply changed their minds and no longer want to go.
How to Read a Policy Before You're in a Crisis
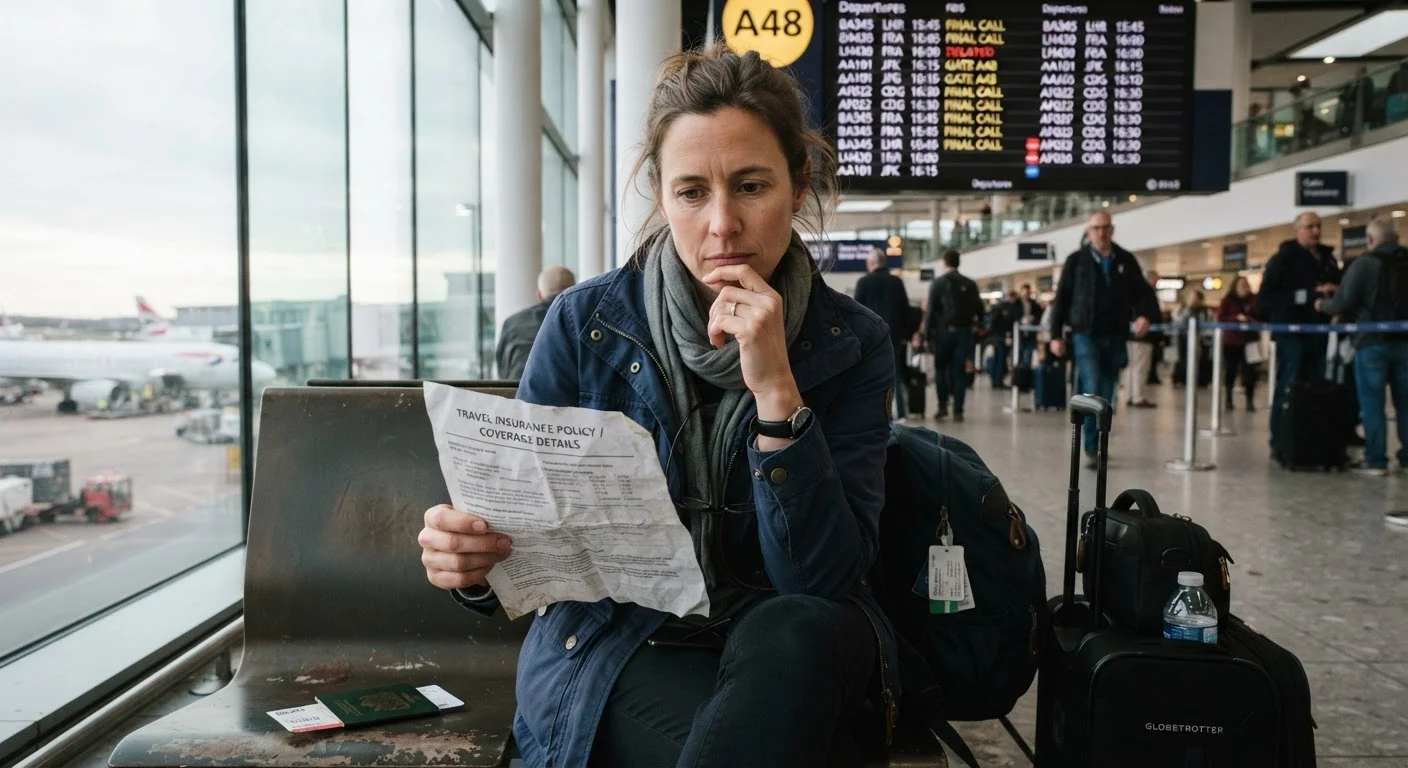
The summary card or marketing brochure that comes with a travel insurance quote is not the policy. The full policy document - often called the Certificate of Insurance or Description of Coverage - contains the actual definitions, covered reasons, exclusions, and claims procedures. Reading it before you travel (not after something goes wrong) is essential.
Pay particular attention to these sections:
- Definitions: Terms like "covered reason," "pre-existing condition," and "traveling companion" have specific legal meanings that determine whether your claim qualifies.
- Exclusions list: This is where most claim denials originate. Read it in full.
- Coverage limits and sub-limits: Baggage coverage may cap electronics at a few hundred dollars. Medical coverage limits vary widely between policies.
- Claims deadlines: Most policies require you to file within a set timeframe after the event - sometimes as short as 20 days.
Check Your Credit Card Benefits First
Many travel rewards credit cards include trip cancellation, baggage delay, or travel accident protection as a built-in cardholder benefit when you pay for the trip with that card. Before purchasing a standalone policy, review your credit card's benefits guide to understand what's already in place - you may be duplicating coverage unnecessarily.
Travelers often carry misplaced assumptions about coverage. Our piece on common travel myths explores related misconceptions that affect trip planning broadly.
When Travel Insurance Matters Most
Travel insurance isn't equally valuable for every trip. The situations where it typically provides the greatest protection include:
- International travel, where your U.S. health insurance likely won't pay foreign hospital bills and medical evacuation costs can run $50,000 or more.
- Trips with large non-refundable deposits - cruises, guided tours, or peak-season bookings where cancellation means losing substantial money.
- Travel involving health vulnerabilities - older travelers or those with complex medical histories face statistically higher odds of a medical disruption mid-trip.
- Remote destination travel, where evacuation logistics are complicated and expensive.
For shorter domestic trips with flexible booking terms, your existing health insurance, credit card travel protections, and airline policies may provide enough of a safety net without purchasing a separate policy. Check what you already have before you buy. And be aware that travel insurance is only one layer of trip cost awareness - unexpected travel expenses can surface in many other ways too.
This article is for general informational purposes only and does not constitute insurance or financial advice. Policy terms, coverage, and exclusions vary by insurer and state. Always read your full policy documentation and consult a licensed insurance professional with questions specific to your situation. Verify current entry requirements, travel advisories, and insurance regulations with official government and provider sources before traveling.